+44 (0) 1908 774320
   
Roger Eddowes

Essendon Accounts & Tax

Home of the Business Godparent ...

What's changing with tax on an overdrawn Director's Loan Account in April?

Roger Eddowes

CREATED BY ROGER EDDOWES

Published: 12/03/2026 @ 09:00AM

#overdrawn Director's Loan Account #Section455 #HMRC #DirectorsLoans #CompanyInsolvency #UKTax

Here's the practical change: Section 455 rises from the 6th of April 2026. If there's an overdrawn Director's Loan Account, the timing of the loan suddenly matters more. This is a quick, conversational run-through of what shifts and why it matters ...

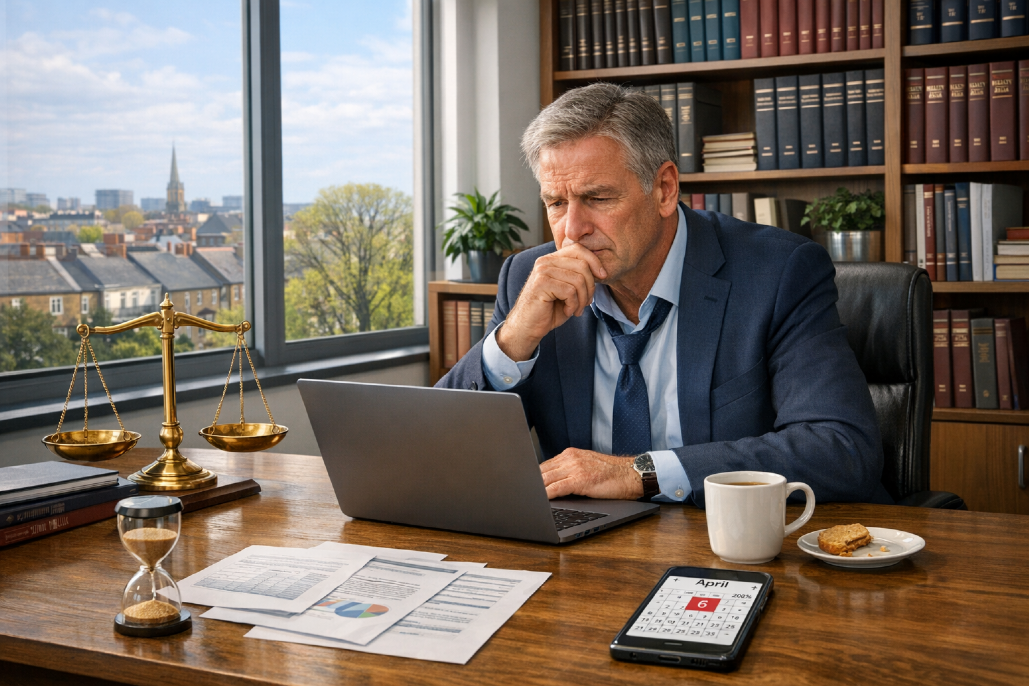
Overdrawn Director's Loan Account, Numbers in the red, A debt to repay

Overdrawn Director's Loan Account, Numbers in the red, A debt to repay

Most people only look closely at an overdrawn Director's Loan Account when the company hits a rough patch, but from April 2026, the tax cost of getting it wrong becomes even easier to feel. HMRC is increasing the Section 455 charge for close companies on loans made on or after the 6th of April 2026, and while it's 'only' two percentage points, it's the sort of change that can quietly turn an inconvenient balance into an expensive one.

It's not just the amount borrowed, but when the borrowing happened and whether it gets cleared in time!

The headline change is simple: the HMRC Section 455 rate moves up to 35.75% for relevant loans made on or after the 6th of April 2026. For context, loans taken on or after the 6th of April 2022 have been charged at 33.75%, and older loans can still be within the earlier 32.5% regime.

This is why conversations about an overdrawn Director's Loan Account increasingly start with dates, because the same balance can carry different outcomes depending on when it arose and how it's repaid.

It also helps to be clear about what Section 455 is actually doing. It isn't income tax on the director, and it isn't Corporation Tax in the usual trading-profit sense; it's a company-level charge that applies when a close company has effectively lent money to a participator, commonly a director-shareholder, and that loan remains outstanding beyond the permitted window. In plain terms, it's designed to stop directors taking value out as 'loans' indefinitely, and it sits right at the junction of Director's Loan Account rules and company director tax planning.

That junction is exactly where many businesses
drift into trouble!

A director takes drawings during a strong period, expects to sort it later through dividends, bonuses, or repayment, and then trading deteriorates, and the plan never lands. The result is an overdrawn Directors' Loan Account that becomes sticky just when cash is tight, and the Section 455 charge can feel like a penalty for being short of funds at precisely the wrong moment.

The 2026 increase matters because it raises the price of leaving things unresolved. If a loan is made after the 6th of April 2026 and remains within charge, the company is potentially paying 35.75% of the relevant balance as the Section 455 charge. That can be a meaningful sum for even modest overdrawing, and it's money the business may struggle to find if it is already under pressure from creditors, rising costs, or declining revenue.

It's worth separating the tax issue from the legal and insolvency reality, because they often collide. In an insolvency process, an overdrawn Director's Loan Account is typically treated as an asset of the company, meaning it can be pursued for the benefit of creditors rather than quietly disappearing. So the director can face two different kinds of pressure at once: the company's exposure under HMRC Section 455 and the practical demand to repay a debt that is now being scrutinised.

Some assume a write-off is an easy
solution, but it usually isn't!

Writing off an overdrawn Director's Loan Account can trigger company director tax consequences for the individual, because HMRC may treat the written-off amount as a distribution or earnings depending on the circumstances. And if the company later enters liquidation, the write-off itself won't necessarily stop enquiries or recovery action, particularly where an office-holder considers the transaction unfair or not properly justified.

Timing, documentation, and intent become unusually important under the Director's Loan Account rules. When the records are poor, the narrative gets filled in by someone else, whether that's HMRC, a liquidator, or a creditor's solicitor, and that is rarely comfortable for the director involved.

A well-kept loan account and a realistic plan to clear it are not just good housekeeping; they can be the difference between a contained tax issue and a wider dispute about conduct and recoveries.

The most useful way to think about the April 2026 change is that it increases the friction in the system. Directors already juggling cashflow may be tempted to let the account drift, but a higher HMRC Section 455 rate increases the downside of delay, and insolvency risk increases the chance that the balance will be actively chased anyway. Put bluntly, the room for “it'll be fine later” shrinks, because later can arrive with both a tax bill and a demand for repayment.

In practice, the sensible approach is to treat an overdrawn Director's Loan Account as an early-warning indicator rather than a footnote in the year-end accounts. If repayment looks uncertain, or the company is moving towards distress, getting advice early can clarify what is realistically possible, what the company can afford, and what the director's personal exposure might be under company director tax rules.

With the 6th of April 2026 rate change approaching, a little planning now can prevent a much more expensive conversation later about an overdrawn Director's Loan Account.

Until next time ...


ROGER EDDOWES
Join our mailing list! Click here and be one of the first to know when we publish a new blog post!


Would you like to know more?

If anything I've written in my blog post resonates with you and you'd like to discover more of my thoughts about an overdrawn Director's Loan Account, then do call me on 01908 774320 and let's see how I can help you.

Don't forget to stay updated with our daily social media posts on Facebook.

Share the blog love ...

Share this to FacebookBuffer
Share this to FacebookFacebook
Share this to TwitterTwitter
Share this to Linkedin (popup window)Linkedin
Share this to Pinterest (popup window)Pinterest
Share this to WhatsApp (popup window)WhatsApp

#overdrawn Director's Loan Account #Section455 #HMRC #DirectorsLoans #CompanyInsolvency #UKTax

About Roger Eddowes ...

Roger Eddowes 

Roger trained at Edward Thomas Peirson & Sons in Market Harborough before working at Hartwell & Co, followed by Chancery, as a partner. He started Essendon Accounts and Tax with Helen Beaumont in 2014 as a general practitioner with a hands-on approach.

Roger loves getting his hands dirty, working with emerging, small-to-medium and family businesses to ensure they receive the best possible accountancy advice. Roger utilises an extensive network of business contacts to leverage the best guidance and practical solutions.

More blog posts for you to enjoy ...

Click here to view this blog post


Inheritance Tax on pensions: What the 2027 rules mean for your family

The rules surrounding Inheritance Tax on pensions are changing in 2027, and anyone hoping to leave their pension savings to loved ones should be aware of what lies ahead ......

Click here to view this blog post


The 60% Tax Trap: Why Earning More Could Leave You Worse Off

Most people assume that earning more means taking home more money. Unfortunately, the 60% tax trap reminds us that the UK tax system isn't always straightforward. For higher earners approaching £100,000, a pay rise or bonus c...

Click here to view this blog post


Budget tax changes: What could they mean for businesses and investors?

As the next budget approaches, speculation about tax changes is gaining momentum. The Chancellor faces a difficult balancing act: managing public finances, encouraging economic growth, and avoiding further pressure on busines...

Click here to view this blog post


Working lunch tax rules: When do sandwiches become a tax problem?

There is something wonderfully British about gathering colleagues around a table, ordering a few sandwiches and calling it a productive meeting. After all, everyone needs lunch, and discussing business while eating seems perf...

Click here to view this blog post


State Pension Triple Lock changes: What could they mean for your finances

The recently announced State Pension Triple Lock changes mark a significant shift in how the State Pension could increase in the future. The existing triple lock will remain in place until April 2030, but after that the earni...

Click here to view this blog post


A Director's Loan Account is useful, but it isn't your personal ATM

A director's loan account can be a normal, useful part of running a limited company. It records money moving between a director and their business that isn't salary, a dividend or reimbursement of a genuine business expense ....

Click here to view this blog post


Is the State Pension triple lock sustainable for the long term?

The state pension triple lock has played an important role in protecting pensioners from falling behind as wages and prices rise. For many people, particularly those with little other retirement income, that protection matter...

Click here to view this blog post


Cybersecurity risks for businesses: Why basic protection matters more than ever

Cybersecurity risks for businesses continue to evolve, and recent incidents show that it is no longer enough to think of cybersecurity as something that concerns only large organisations or technology companies. The ways a bu...

Other bloggers you may like ...

Click here to view this blog post


What happens if you don't check in with YourPING?

Posted by Steffi Lewis on https://www.yourping.uk

Life gets busy, and even simple things can slip our minds. You might be enjoying a long conversation with a friend, working in the garden, watching a ...

Click here to view this blog post


Are you an overseas visitor looking to stay in Milton Keynes?

Posted by Emily Freeman on https://blog.shortstay-mk.co.uk

Overseas visitors seeking a base in Milton Keynes will find we offer an exceptional range of serviced accommodation tailored to their needs. Discover ...

Click here to view this blog post


Turning setbacks into opportunities: How difficult times can lead to new beginnings

Posted by Dave Cordle on https://blog.davecordle.co.uk

Life doesn't always go according to plan, does it? Sometimes events happen that completely knock us off course, whether that's redundancy, a business ...

Click here to view this blog post


How charities and community groups can use our daily check-in service

Posted by Steffi Lewis on https://www.yourping.uk

Charities and community groups do extraordinary work supporting people who might otherwise feel isolated, overlooked, or disconnected. Whether helping ...

© 2026 by Roger Eddowes

All rights reserved


All content on this blog, including but not limited to text, images, videos and audio, is protected by copyright. No part of this blog may be reproduced, copied, distributed, or otherwise used without the prior written consent of the author. Unauthorised use constitutes a breach of intellectual property rights.

Please note that many elements of this blog have been created using Artificial Intelligence (AI). As such, content may not always reflect verified facts or professional advice. The information provided is for general interest only and should not be relied upon as a sole source for making decisions, financial or otherwise. Readers are strongly advised to seek independent advice from qualified professionals appropriate to their country and situation.

The author of this blog, YourPCM Limited, and its directors, employees, and authorised agents accept no liability for any loss, harm, or consequence arising from the use or interpretation of content found on this site.

The sblogit.com platform is provided on an “as is” basis. By continuing to view or interact with this blog, you acknowledge and accept these terms. If you do not agree with any part of this notice, please cease using this site immediately.

YourPCM Limited is a company registered in the UK and operates exclusively under the jurisdiction of the laws of England and Wales.